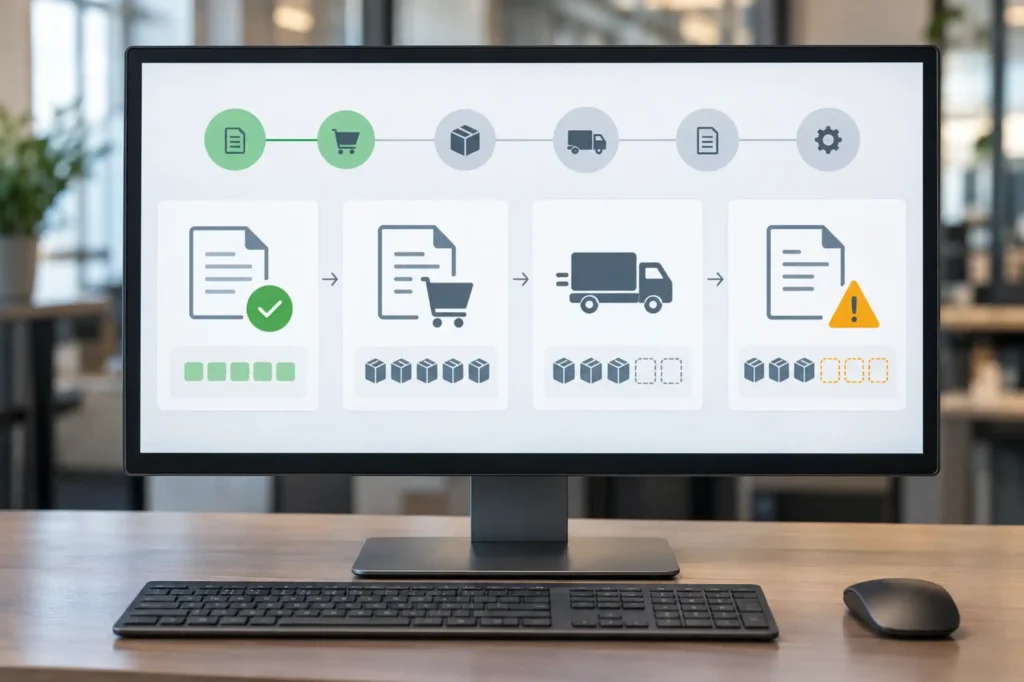
Procurement Automation Process: Six…
A purchase request can sit unanswered while a supplier waits…
A forgotten software renewal can be harder to explain than a large, carefully approved order. When everyday purchases happen across separate teams, the full cost is easy to miss.
For businesses, indirect procurement means buying goods and services that support internal operations rather than form part of the offering sold to customers. The work extends from clarifying a need to selecting suppliers, agreeing terms, and confirming delivery. Clear ownership helps prevent duplicate purchases, missed renewals, and payments for work that nobody has checked.
These purchases provide the services, equipment, and supplies people need to do their jobs. How an item is used determines its category.
Common examples include:
Office furniture, workplace cleaning, and utilities.
Employee computers and software for internal use.
Recruitment, legal advice, and other professional services.
Maintenance, repair, and operations supplies for equipment and facilities.
Business travel and employee training.
For example, suppose a bakery buys flour for its products and bookkeeping software for its office. Flour is a direct input; bookkeeping software supports the business internally.
Price does not decide the classification. A small ingredient order can be direct, while a larger internal technology purchase can be indirect. The same type of purchase may also serve different purposes in different businesses.
Problems develop when buying decisions, contracts, and payment records stay separate. Individual orders may look reasonable while the overall spending pattern remains unclear.
For example, suppose two departments pay for similar software. Neither sees the other’s subscription, and both keep unused accounts through another renewal.
Other gaps are less obvious. Supplier names may differ between records, contracts may sit in personal inboxes, or invoices may arrive without evidence of approval. Delivery charges and cancellation fees can also change the true cost of an apparently inexpensive purchase.
Spend visibility means knowing who bought what, from whom, for which purpose, and at what cost. Category management uses that information to plan related purchases together. Departments can agree common requirements where appropriate and document exceptions where their needs differ.
A useful process makes responsibility clear at each stage. The level of review should reflect the commitment and risk involved.
Explain the need. A purchase requisition records the requirement, purpose, estimated cost, and delivery date. Checking existing stock or contracts first can prevent an unnecessary order.
Obtain approval. The budget owner approves the proposed expense before anyone commits to it. A specialist may need to review additional concerns, such as access to confidential business data.
Assess suitable suppliers. Compare proposals against the same requirements. Price matters, alongside service quality, support, delivery, and the full cost over the agreement’s term.
Document the commitment. Confirm the scope, price, responsibilities, payment terms, and cancellation conditions. Where policy requires a purchase order, issue it before placing the order and retain the supplier’s confirmation.
Check delivery and the invoice. Confirm that the goods arrived or the service met the agreed requirements. Three-way matching compares the purchase order, receipt record, and invoice. Any unexplained difference needs review before payment.
Supplier management continues through performance reviews, complaints, and contract decisions. Assigning an owner to each agreement gives employees a clear contact when something goes wrong.
Useful measures show where the process needs attention. Total spending alone does not reveal why requests stall or invoices need correction.
Practical measures include approval time, invoice discrepancies, unused subscriptions, and purchases outside agreed contracts. Each needs a consistent definition. For approval time, a business might measure from receipt of a complete request to the final decision. Including incomplete requests in some comparisons would distort the result.
Automation can route requests, flag mismatches, and send renewal reminders. Its usefulness depends on accurate records, sensible rules, and someone handling exceptions. A reminder achieves little if it reaches an employee who no longer owns the contract.
Testing one repeatable category makes changes easier to assess. A useful comparison includes processing time, corrections, and service problems before and after the change.
Classify purchases by purpose, regardless of their price.
Keep spending, supplier, and contract records connected.
Set approval requirements according to value and risk.
Assign owners and resolve process gaps before introducing automation.
Better control starts when employees understand how to request a purchase and who must approve it. Reliable records then connect the original need with the agreement, delivery, and payment. That makes duplicate orders, forgotten renewals, and unresolved discrepancies easier to investigate.
Use this Ebtechsol guide to review one spending category and choose a practical improvement, such as assigning contract owners or recording approvals consistently.
Responsibility depends on the stage. Departments explain their needs, procurement supports supplier selection and terms, budget owners approve expenses, and finance checks payment records. Each decision needs a named owner.
Not necessarily. A shared supplier register, a simple request form, and clear approval limits may be sufficient. Software becomes more useful when transaction volume or complexity makes those arrangements difficult to manage.
Yes. An item’s price does not determine its purchasing category. A small component used in a customer product is a direct input because of its role in that product.
Purchasing focuses on placing orders and completing transactions. Procurement also covers the work surrounding those transactions, including defining requirements, comparing suppliers, negotiating agreements, and reviewing performance over time.
Maverick spending means buying outside agreed purchasing arrangements. Employees may bypass approved suppliers or procedures because of urgency, unclear instructions, or delays. Understanding the cause helps identify a suitable response.
No. Tail spend generally describes many suppliers or purchases accounting for a relatively small share of total spending. It may include direct and indirect purchases, so the terms describe different things.
Quote requirements depend on purchasing policy, value, and risk. An order under an existing agreement may require less comparison than an unfamiliar service with a lengthy commitment or uncertain scope.
An emergency route should specify who can approve the expense and what records to retain. Reviewing the purchase afterwards helps explain the exception and identify problems that better planning could prevent.
Heavy reliance on one supplier can make disruption harder to manage. Performance reviews should consider service reliability, available alternatives, and the effort required to move essential purchases elsewhere.
Owners should check actual usage, supplier performance, pricing changes, and notice deadlines. Starting the review early leaves time to agree new terms, cancel unused services, or arrange a replacement.
A purchase request can sit unanswered while a supplier waits…
Late deliveries can disrupt work even when a purchase looked…
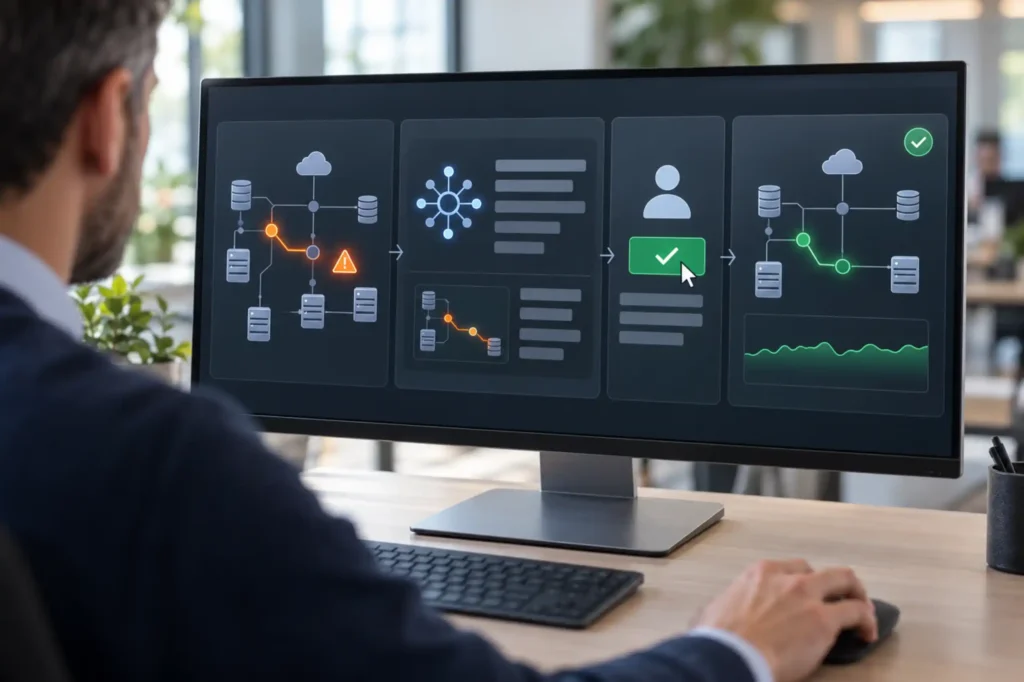
An invoice workflow can fail because of a weak integration,…

EB Technical Solutions FZE /
EB TECHNICAL SOLUTIONS (PVT.) LIMITED
Copyright © 2026 EBTECHSOL

Ask me anything about AI Automation, API Integration, SaaS Development or our Services.
Just get in touch via text or microphone.